

Chime – Mobile Banking
Chime
- 4.7
- 226.90K Reviews
- 10.00M
- Downloads
- Free
- Price
Screenshots
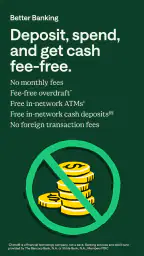
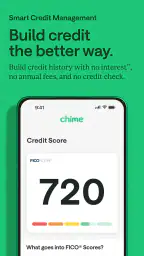
Chime – Mobile Banking Pros and Cons
Pros
- No monthly fees for standard accounts.
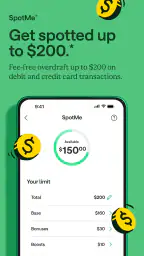
- Fee-free overdrafts up to $200.
- Instant transaction notifications.
- Easy mobile check deposit feature.
- Wide ATM network availability.
Cons
- No physical bank branches available.
- Limited international banking services.
- Cash deposit fees at some locations.
- No joint or business accounts offered.
- Mobile-only platform, no web access.
 Analysis by All-app
I’m most interested in whether a banking app stays understandable when I’m checking it quickly, using a smaller screen, or trying to manage money while life is already busy. Chime – Mobile Banking is built around phone-based banking rather than visits to a branch, and that can make routine tasks feel more immediate. My overall impression is that its appeal depends less on flashy tools and more on whether its everyday approach fits the way you already handle paychecks, spending, and savings.
Readability and finding your way around
For me, a useful finance app should help me answer practical questions without making me hunt: Has my pay arrived? What did I spend? Is there enough in the account for the next bill? Chime’s mobile-first design is intended to keep banking close at hand, which is especially useful when I want a quick check rather than a full budgeting session. A clear screen can reduce the mental effort of checking balances, but it does not replace the value of taking time to review transactions carefully.
I would treat the app as a convenient place to monitor day-to-day activity, not as a substitute for a complete financial plan. If I were comparing it with a traditional bank’s app, I’d focus on whether the core account information I use most is easy for me to locate and understand. People who want detailed household budgeting, investment tracking, or a consolidated picture of accounts at several institutions may still prefer a separate finance tool or a bank that better matches those needs.
Motor and sensory considerations
Phone banking can be a relief for someone who finds branch visits difficult, but it also puts more weight on touch controls, screen presentation, and the phone itself. In practice, I’d try the ordinary tasks first: checking a balance, reviewing recent activity, and finding the account settings I need. That gives a better sense of whether the app’s layout and interaction style work comfortably for my hands and eyesight than relying on a general claim that any mobile interface is easy.
For sensory comfort, the real test is whether I can use it in my own conditions: with the display settings I prefer, in a quiet moment or a noisy place, and without feeling rushed by alerts. Chime’s account activity can be useful to keep an eye on, but frequent notifications may not suit everyone. I’d tune the phone’s notification settings to the level of interruption I can handle, while making sure I still notice information that matters to me.
When access depends on the situation
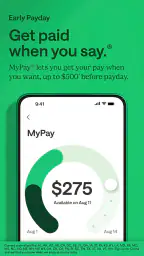
The strongest case for a phone-based bank is often a small, time-sensitive task. If I’m away from home and need to check whether money has arrived before making a purchase, an app can save a trip and a wait. Chime’s early-payday appeal may also help someone whose pay arrives through direct deposit and who values seeing it sooner; I’d still plan bills around the deposit timing I can rely on rather than treating early arrival as guaranteed for every pay cycle.
That convenience depends on having a working phone and a connection when I need the account. I’d keep another way to reach essential funds available if my battery dies, I lose service, or I can’t comfortably use a screen at that moment. This is not a special flaw of Chime so much as a trade-off of making a phone the main doorway to banking, but it matters if cash access is urgent or predictable access is essential.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What could still get in the way
Moving routine banking onto a phone does not make every part of banking effortless. A person who prefers in-person help, needs services beyond everyday spending and saving, or wants a single place for complex financial planning may find a mobile-first account limiting. I’d also check that the account’s available services suit my circumstances before moving direct deposits or making it my only banking option. The right choice is the one that handles my real routine, not simply the one with the neatest interface.
There is also a difference between a feature sounding helpful and fitting a person’s actual habits. Automatic saving can make progress feel painless, but small round-ups are not a complete savings strategy, and I would want to understand how the transfers affect my available balance before relying on them. Early access to pay can ease timing pressure, yet it should not become a reason to spend money before essential bills are covered. Those are practical boundaries I’d keep in mind with any account built to make money feel readily accessible.
What is Chime?
So, what’s the deal with Chime? It’s basically a mobile banking app that’s designed to simplify your life. Forget about those long queues at the bank; with Chime, you’ve got everything you need right on your smartphone. It’s got a slick, user-friendly interface that makes managing your money a breeze. And the best part? No hidden fees!
Features that Stand Out
One of the coolest features has to be the early direct deposit. You know how payday always seems too far away? Well, with Chime, you can get your paycheck up to two days early. It’s like a financial time machine, and who wouldn’t want that?
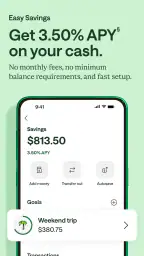
Another great feature is the automatic savings program. Every time you make a purchase, Chime rounds up the transaction to the nearest dollar and stashes the difference in your savings account. It’s like having a little digital piggy bank that’s always working, even when you’re not.
Keeping Your Money Safe
Now, I know what you’re thinking. Is my money safe with Chime? Absolutely! They’ve got all the security bells and whistles you’d expect from a bank. Your money is FDIC insured up to $250,000 through their partner banks, and they use encryption and real-time alerts to keep your account secure. So, you can sleep easy knowing your cash is well-protected.
Customer Experience
Let’s talk about the user experience. Navigating the app is as easy as pie. Setting up your account takes just a few minutes, and if you run into any hiccups, their customer service is top-notch. Whether it’s through chat, email, or phone, they’re always ready to help you out. It’s this kind of service that makes you feel valued as a customer.
Who is it For?
If you’re someone who’s always on the go and hates dealing with traditional banks, Chime is perfect for you. It’s designed for the tech-savvy crowd who prefer managing their finances digitally. Students, freelancers, and even regular 9-to-5 folks can benefit from the convenience it offers.
Everyday use: where the convenience pays off
A realistic use case is a worker who checks their pay before setting up the week’s spending. If a direct deposit arrives early, they can use that breathing room to schedule groceries, transit, or a bill without waiting for the usual payday. I’d still keep a simple calendar or reminder for fixed expenses: an earlier deposit can help with timing, but it does not change when rent or other obligations are due. The useful habit is to treat the extra time as planning room, not as extra income.
The round-up saving approach works best, in my view, when purchases are already part of a steady routine and the transfers remain comfortable. Someone with a tight balance could review the effect of small transfers before leaving the feature to run automatically. Someone with an irregular income might instead move a deliberate amount after each deposit, once essential costs are accounted for. Those two approaches solve different problems, and the app’s automated option is not automatically the best fit for every budget.
How it compares with other ways to bank
Compared with a branch-centered bank, Chime puts more emphasis on handling everyday account tasks through a phone. That suits people who rarely need face-to-face service and would rather check activity on their own schedule. A traditional bank may be a better match for someone who values branch access or already depends on a broader set of banking services. I would compare the actual services I use, not assume that a mobile-first experience is superior in every situation.
Against a basic account with another digital bank, the practical differences are likely to come down to the specific features and service experience that matter to me: early direct deposit, fee-free overdraft, how I prefer to save, and how comfortable I am resolving questions remotely. Chime’s summary highlights no monthly fees and fee-free overdraft, but I would read the current account terms closely before relying on any overdraft feature. “Fee-free” does not mean I should treat overdrawing as a budgeting strategy; it is better understood as a possible short-term cushion than a replacement for keeping track of spending.
Choosing it for your own routine
I can see Chime working well for someone who wants a straightforward mobile account, has regular direct deposits, and is comfortable doing most banking without a branch visit. It may also suit a student or a freelancer who wants a simple way to keep routine money activity visible, provided the account’s services fit their personal situation. The app is free, comes from finance developer Chime, and is rated for Everyone. It has a 4.7 average from around 946,000 ratings, with over 10 million installs; those figures suggest broad use, but they cannot tell me whether its interface or service will suit a particular person.
I would be more cautious if I needed extensive in-person support, relied on cash-heavy routines, or wanted sophisticated tools for planning several accounts together. Before switching my main income or bills, I’d confirm that the account can support the payments and access methods I actually depend on, then try it alongside my existing arrangement if that is practical. That makes it easier to spot a mismatch before a missed payment or an inconvenient cash-access problem becomes urgent.
Practical questions before making the switch
One question people often have is whether early pay means a deposit will always show up ahead of the expected date. I would not build a budget around the earliest possible arrival. Pay timing can depend on when the payer sends the deposit, so I’d plan using the date I can safely count on and regard an earlier arrival as a bonus. That approach preserves the convenience without turning a variable timing benefit into a financial assumption.
Another sensible question is whether an app can replace every reason someone keeps a conventional bank account. For some people, it may handle most routine needs; for others, branch access, cash services, or a particular account feature may make a second option useful. I’d also consider what I would do if my phone were unavailable. Keeping a backup plan for essential payments and access is not overcautious when a phone is the main way I manage money.
For anyone who needs a more accessible way to bank, I’d make the decision through direct use rather than assumptions. Try the tasks that matter most, adjust the phone’s display and notification settings, and notice whether the app remains comfortable during a rushed moment as well as a quiet one. If a control is hard to reach, information is difficult to read, or alerts create stress, that friction matters more than a general reputation for ease of use. A different app or a bank with in-person help may be the more inclusive choice for that person.
My inclusive verdict
Chime’s strongest case is practical: it brings routine banking onto a phone and pairs that with features that can help people manage the timing and small habits of their money. I like the possibility of checking activity without arranging a branch visit, while the automatic round-up idea offers a low-effort starting point for saving. The main trade-off is that convenience depends on a phone-based workflow, and the experience will not be equally comfortable or sufficient for everyone.
Chime – Mobile Banking was released on March 28, 2014, and its current version is 5.301.0 for operating systems version 10 and later. I would recommend considering it if mobile access, early-payday convenience, and a low-friction routine matter more to you than branch support or advanced financial planning. It is not a universal answer, but for someone whose needs match its approach, it can make everyday banking feel more manageable. In conclusion, Chime – Mobile Banking is more than just an app; it’s a lifestyle change. It brings banking into the 21st century and makes managing money less of a chore and more of a seamless experience. So, if you’re ready to take control of your financial future, give Chime a try. You might just wonder how you ever lived without it!
Frequently Asked Questions
What is Chime Mobile Banking?
Chime Mobile Banking is a financial technology company that offers banking services through a mobile app. It provides users with features like no-fee overdrafts, early direct deposits, and a network of fee-free ATMs. It's designed to offer a straightforward and user-friendly banking experience without traditional bank fees.
How secure is Chime Mobile Banking?
Chime prioritizes user security by employing encryption and secure processes to protect personal information. It provides security features such as two-factor authentication and instant transaction alerts, ensuring users can monitor their accounts closely. Additionally, Chime is insured by the FDIC, providing peace of mind for users concerning their deposited funds.
Are there any fees associated with using Chime?
Chime is known for its no-fee policy on many standard banking services. There are no monthly fees, minimum balance fees, or overdraft fees. Additionally, users can access a network of over 60,000 fee-free ATMs. However, fees may apply in certain situations, such as out-of-network ATM withdrawals.
What features does Chime offer for managing finances?
Chime offers several features to help users manage their finances effectively. These include automatic savings tools, real-time transaction notifications, and spending insights. Its SpotMe feature allows eligible users to overdraft up to $200 without fees. Additionally, users can receive direct deposits up to two days early, providing faster access to funds.
How can I sign up for Chime Mobile Banking?
Signing up for Chime is a simple process that can be completed entirely online. Users need to download the Chime app from the App Store or Google Play and provide basic information to create an account. Approval is typically quick, and once approved, users can start using the app to manage their finances immediately.


